- Home
- How we test
How we test
A backtest is only useful if it could have failed. These rules are fixed before any result is seen.
The four rules
Every TradeLab study and bot test follows the same method.
Chronological splits
Rules are tuned on development data only, never on the data that judges them.
Registered final test
The final test and its pass rule are written down and hashed before its data is opened.
Real costs
Recorded spreads, fees and overnight financing are charged on every simulated trade.
Luck tests
A result must beat hundreds of coin-flip and random-entry runs on the same trades.
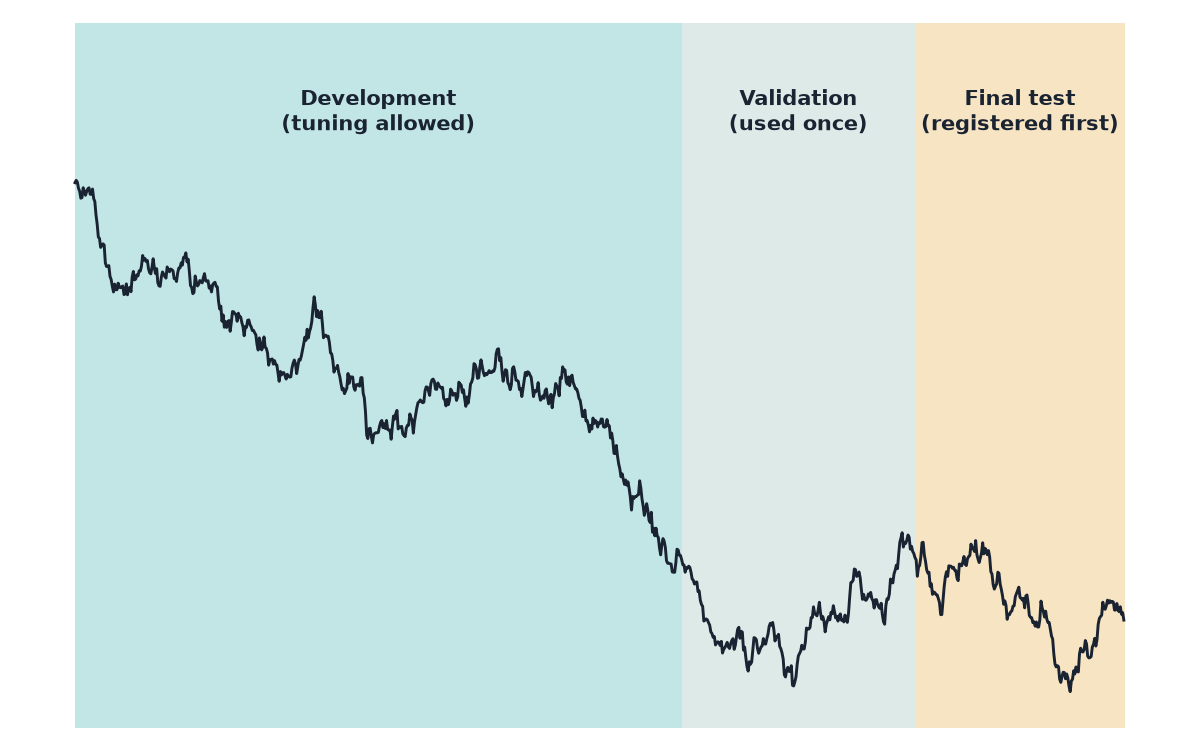
Split history in time order
Development data is for building and tuning. Validation data is opened once to choose. The final period is opened last, under a test registered in advance. No second chances on the same data.
Beat luck
The same entries with random directions, and random entries on the same bars, are run hundreds of times. A strategy must do better than at least 95% of them.
Charge every cost
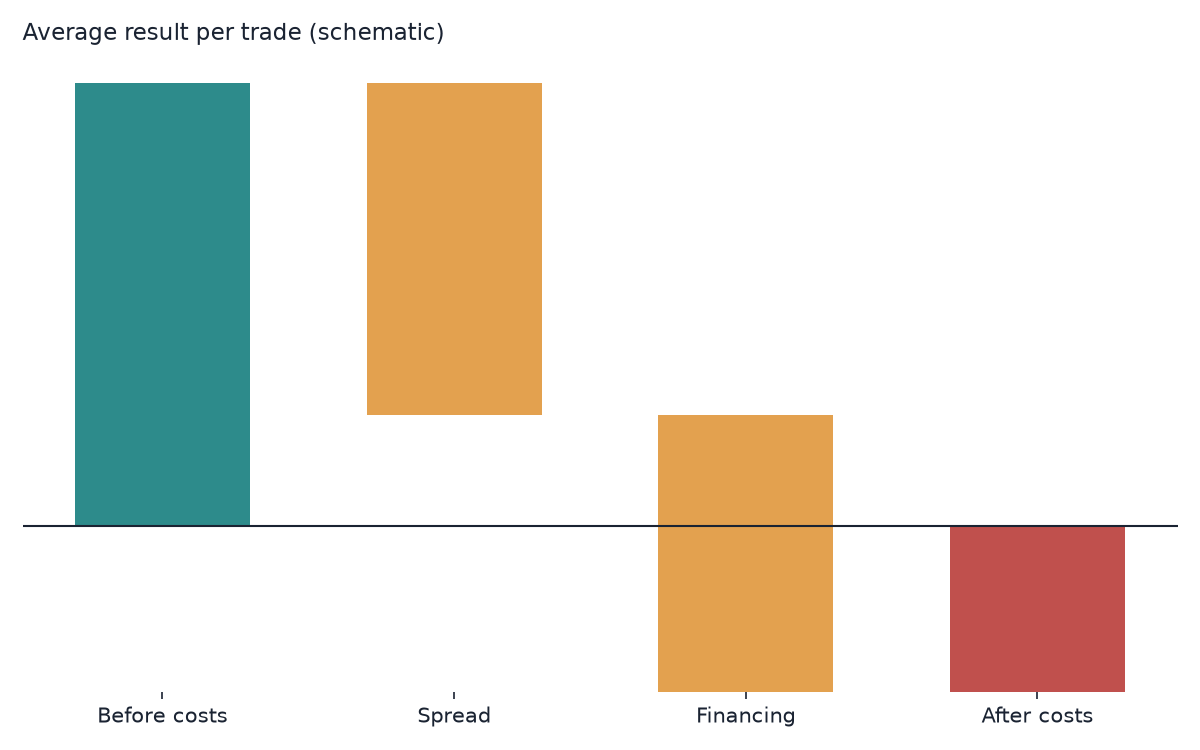
The broker’s recorded spread at each fill, commissions where they apply, and overnight financing for positions held past the close. A rule can be positive before costs and negative after them.
Publish the failures
A strategy that fails its test is reported with the same detail as one that passes. Most ideas fail; knowing which ones saves money.
Every result is a historical simulation. It is not investment advice and not a promise of future returns.